Tag: Cross-Border Payment

  • Beyond Cash Pickup: Modern Remittance Payout Options Driving Adoption in Cross-Border Payments Africa

    Beyond Cash Pickup: Modern Remittance Payout Options Driving Adoption in Cross-Border Payments Africa

    In the early days of cross-border payments in Africa, cash pickup solved a real problem. 

    Limited banking infrastructure meant physical cash was the only reliable endpoint. So money service businesses, remittance operators and even the early digital remittance startups had to make avenues for cash pick-up operations.

    Today, that assumption is breaking.

    More Africans than ever are using some sort of mobile device or have access to the internet. More users now expect remittance to be digital, fast and match the speed and flexibility of the rest of their financial lives. 

    They don’t want to queue in front of cash pick-up shops, or depend on agents’ availability. They want money to arrive where they already transact: on their mobile money wallet, their remittance app wallet or their bank account!

    That shift is redefining payout options for remittance in Africa, changing the “tools” necessary to operate a successful remittance business today and who’s winning in the increasingly “digitalised money” era in Africa.

    The Hidden Limitations of Cash Pickup
    Woman putting banknotes in a wallet

    Cash still plays a role, but its limitations are becoming harder to ignore, especially at scale.

    1. Cost inefficiencies
    Cash logistics aren’t cheap. You’re dealing with agent commissions, liquidity management, and physical infrastructure. That cost either eats your margins or gets passed to users.

    2. Accessibility gaps
    Even in markets where agents are widespread, they’re not always convenient. Distance, operating hours, and local security concerns all introduce friction.

    3. Operational bottlenecks
    Cash-heavy networks are harder to scale. Reconciliation is slower, fraud risk is higher, and service reliability depends on third-party agents behaving perfectly every time—which, as most operators know, is optimistic.

    For founders thinking about alternatives to cash pickup remittance, these aren’t edge cases. They’re daily realities.

    Remittance Payout Options That Actually Drive Adoption Today

    Today’s generation of remitters and their beneficiaries expect more payout options from remittance businesses beyond cash, optimised for how they already live and transact. Here are modern payout options your business should support:

    1. Bank Transfer Remittance

    Bank transfer remittance remains one of the most trusted payout methods globally.

    It works because funds land directly in the recipient’s account. It supports higher transaction values and greatly aligns with formal financial systems anywhere in the world.

    In many African corridors, improving bank connectivity has made this option faster and more reliable than ever. For certain segments—SMEs, salaried workers—it’s often the default.

    2. Mobile Money Payouts
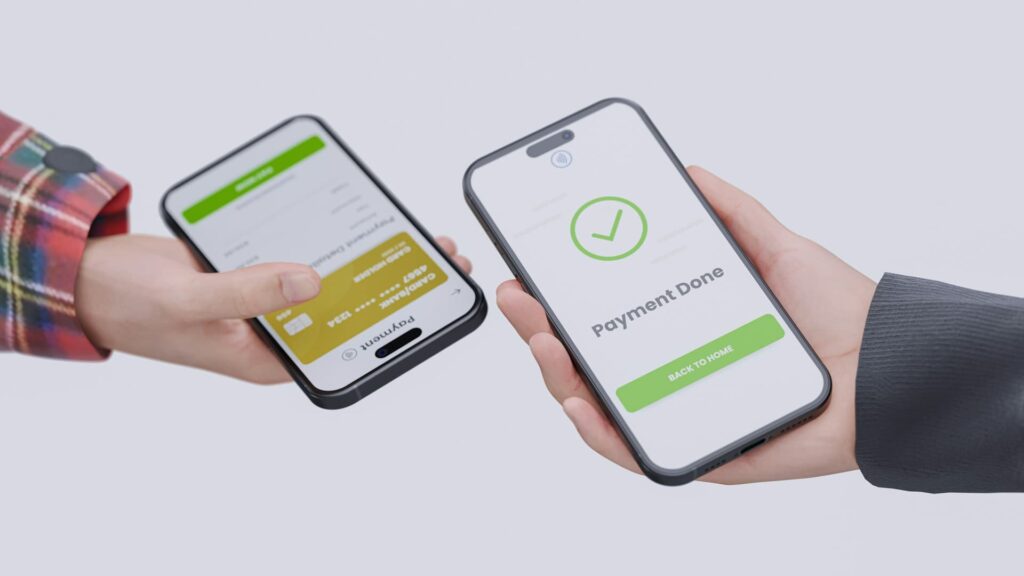
    bank transfer - RemitJuncttion

    Mobile wallets have effectively become the primary financial interface in several markets. Users don’t just store money there; they spend, save, and transact daily.

    It works because funds are made instantly available on the recipient’s mobile device. There is also no dependency on traditional banking. Mobile wallets are used in both urban and rural areas.

    For digital remittance solutions, this is where volume, and loyalty, often comes from.

    3. Digital Wallets
    Card payment - RemitJunction

    Beyond mobile money, broader digital wallets are gaining traction, especially in more connected markets.

    They offer faster settlement cycles, seamless integration with apps and services, and a gateway into ecosystem-based financial services.

    For operators looking at how to improve remittance adoption rates, wallets create stickiness. Once funds land in a digital ecosystem, users tend to stay within it.

    4. Airtime and Bill Payments

    Instead of sending money to be withdrawn, remitters could send value to be used directly in the form of airtime, data, utilities, or subscriptions for various needs like electricity, medical care or education.

    Embedding these payment forms into your remittance payout options reduces cash-out pressure, increases transaction frequency and creates additional revenue streams.

    It’s a subtle shift, but one that many digital remittance solutions are leveraging to deepen engagement.

    5. Agent-Assisted Hybrid Models

    Cash isn’t dead, it’s simply evolving. As a result, human agent networks are still needed. 

    However, your agent network should operate a hybrid model where digital payouts can be facilitated at the agent’s shop with assisted cash-out where needed. Think:

    • Pre-funded agent withdrawals via mobile alerts
    • QR-based pickup instead of manual verification

    These models retain the reach of cash while improving efficiency, offering practical alternatives to cash pickup remittance without fully removing it.

    Africa’s Reality: Mobile First, Infrastructure Mixed
    Map of Africa showing some African countries

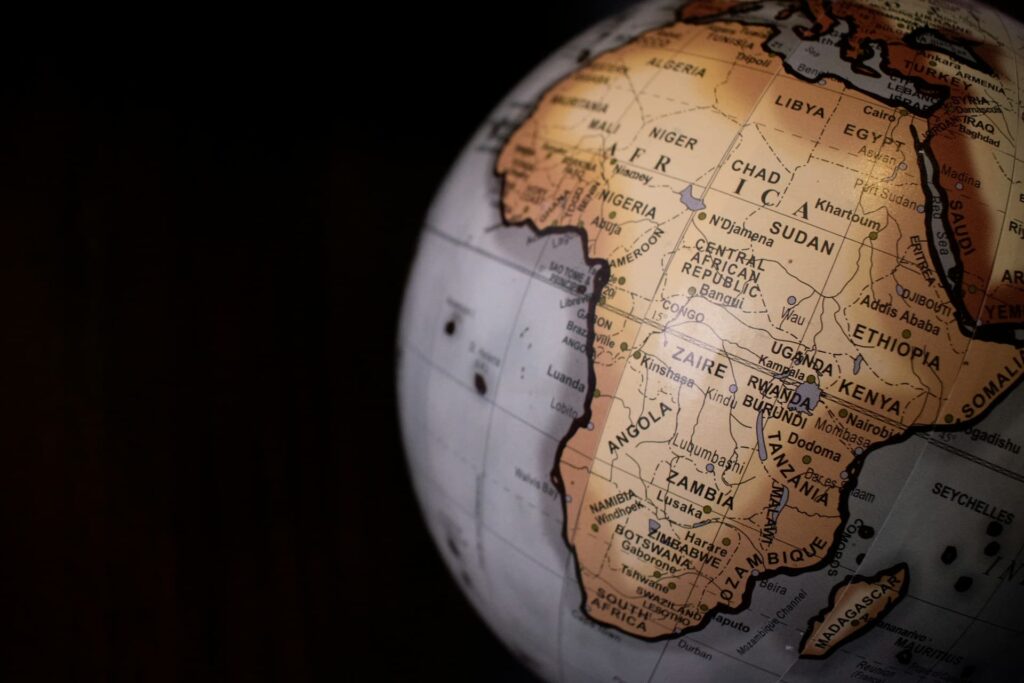
    The African payments landscape is not uniform.

    On one hand, mobile money payouts dominate in markets like Kenya and Ghana. On the other, bank transfer remittance is still critical in more banked economies. Meanwhile, infrastructure gaps persist in certain regions.

    This creates a fragmented environment where no single payout method wins everywhere.

    For money transfer operators, this means one thing: flexibility is not optional.

    The real winners in cross-border payments Africa are those who can dynamically offer multiple remittance payout options, adapting to corridor-specific behaviour without rebuilding their stack each time.

    This guide on How to Launch a UK–Africa Remittance Corridor Without Building Infrastructure shows you a practical example of how payout flexibility plays out in real corridors.

    How RemitJunction Enables Multi-Payout Flexibility

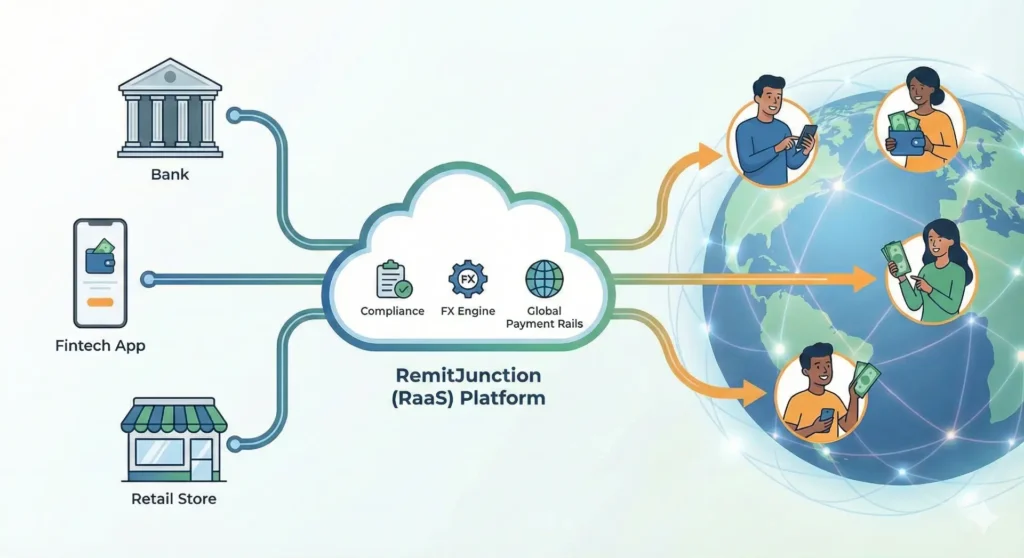
    Given the increasing demand for digital payouts across African remittance markets, leveraging RemitJunction’s distinct digital infrastructure can become your competitive edge.

    Behind every seamless payout experience is a switching layer coordinating:

    • Multiple payout partners
    • Different settlement rails
    • Real-time routing decisions

    RemitJunction’s approach is built around this principle. Through our API-based infrastructure, you can:

    • Integrate diverse payout methods—from bank transfer remittance to mobile money payouts and more
    • Route transactions based on speed, cost, or availability
    • Expand into new corridors without rebuilding from scratch

    For a closer look at our product layer, you can explore Inside RemitJunction’s White-Label Remittance Platform, or see how partners go live quickly in How RemitJunction Partners Launch Remittance Business Fast in Weeks.
  • Cross Border Disbursement at Scale: How Banks, Telcos & NGOs Can Move Money Efficiently

    Cross Border Disbursement at Scale: How Banks, Telcos & NGOs Can Move Money Efficiently

    cross-border disbursement at scale

    Let me paint you a picture of a typical scenario that frequently occurs with funds disbursed for humanitarian purposes:

    A humanitarian organization has just secured emergency funding. People on the ground need it urgently. Not in three business days. Not after the wire clears three intermediary banks and loses 4% to fees. Now!

    The programme manager opens a laptop, logs into their disbursement portal, and… waits. The payment file is rejected. Wrong format. They try again. 

    The bank’s API is down for scheduled maintenance. Then they try a workaround. The compliance team flags it. Meanwhile, real people are waiting.

    This happens frequently with institutional cross-border disbursement, whether aid, payroll, grants, or bulk transfers. It’s one of the most chronically underserved use cases in global payments. Organizations that move large volumes of money across corridors consistently run into the same wall: the infrastructure simply wasn’t built for them.

    The good news is that this doesn’t have to be the case anymore. Modern technologies and designs are changing this. If you’re a bank, telco, NGO, or enterprise operating cross-border disbursements at scale, this piece is for you.

    The Real Problem With Institutional Cross-Border Disbursement

    Most enterprise disbursement challenges live deep in the pipelines. That is, the systems and switches that move the money from the senders to the entities. 

    When a telco wants to pay out commissions to agents spread across five African countries, or an NGO needs to fund hundreds of last-mile recipients in Ghana, Kenya, and Senegal simultaneously, the blockers are almost always the same: fragmented payout rails, inconsistent compliance posture across corridors, settlement timing mismatches, and the sheer operational overhead of managing multiple relationships with local partners.

    Throw in the compliance question — AML, KYC, sanctions screening, SAR obligations — and you’re looking at a full-time operation before you’ve moved a single dollar. Most organizations either under-resource this and run the risk of regulatory noncompliance, or over-resource it and erode margins. Neither is a great outcome.

    What institutional senders actually need is a single remittance infrastructure that handles payout diversity, centralises compliance, and gives them programmatic control over the entire disbursement lifecycle.

    What RemitJunction Does to Solve These Problems.

    KYB for businesses

    If you’re evaluating a bulk payment platform for institutional disbursement, the infrastructure conversation has to cover three non-negotiables: payout coverage, compliance architecture, and API depth.

    Payout Coverage That Matches Where Your Recipients Actually Are

    The global South, particularly Sub-Saharan Africa, is not a single market. Nigeria has NIBSS. Kenya has M-Pesa. Ghana has GhIPSS and a thriving mobile money ecosystem. Senegal has Wave. 

    A bulk remittance payments platform that only supports SWIFT wires will strand a significant portion of your recipients in every single disbursement run.

    RemitJunction supports bank transfers, mobile money wallets, and cash pickup agents, often within the same payout batch. This multi-rail payout capability is what separates serious infrastructure from glorified wrappers.

    Centralized Compliance Across Every Corridor You Touch

    Here’s where most organizations get into trouble. They build payout capability but compliance becomes a patchwork of local partners, manual processes, and well-meaning but understaffed teams trying to stay on top of 12 different regulatory environments at once. It doesn’t scale. And regulators notice.

    RemitJunction’s infrastructure runs KYC, KYB, AML screening, sanctions checks, PEP screening, and transaction monitoring from a single compliance engine; not as a checklist, but as a live, automated layer embedded into every transaction. 

    When a disbursement triggers an anomaly flag, it’s caught, held, and reviewed without manual intervention, derailing the rest of the batch.

    API Depth: Programmatic Control for Disbursement API Fintech Use Cases

    For banks, telcos, and enterprises running disbursements at any meaningful volume, manual portals are a dead end. You need a disbursement API fintech solution that lets your systems talk directly to the payment infrastructure,  triggering batch runs, querying transaction states, retrieving settlement data, and handling exceptions programmatically.

    RemitJunction’s API goes further: it gives your finance team real-time reconciliation data, automatically matching disbursement values to settlement confirmations from payout partners. 

    It gives your operations team transaction-state visibility across every leg of the payment — so exceptions surface before they become complaints. And it gives your compliance team an audit trail that doesn’t require a data engineering project to query.

    How RemitJunction Enables Institutional Cross-Border Disbursement

    How RemitJunction Enables Cross-Border Disbursement

    Built as an operational remittance infrastructure for regulated money businesses, RemitJunction has been processing real transactions across live corridors for over a decade, just under a different name, “MTA.”

    As a licensed principal firm, RemitJunction provides regulatory cover that institutional senders need without having to acquire or maintain their own licences. Organizations onboard as appointed agents, operating cross-border payouts under RemitJunction’s regulatory framework. 

    This is particularly valuable for NGOs asking how NGOs send money across borders without drowning in licensing logistics, and for enterprises exploring white-label remittance platforms that let them move fast without building from the ground up.

    On the payout side, RemitJunction’s network covers multiple countries with support for bank transfer, mobile money, and cash pickup — all accessible through the same integration. 

    For organizations running cross-border payroll solutions across Africa, this multi-rail capability means the same disbursement run can credit a bank account in Lagos, top up a mobile wallet in Accra, and route a cash pickup in Nairobi without managing three separate partner relationships.

    RemitJunction’s Remittance-as-a-Service infrastructure handles the compliance layer centrally — KYC/KYB verification, AML and CFT screening, sanctions and PEP checks, automated transaction monitoring, fraud detection, and SAR filing — so institutional senders don’t have to build and maintain this apparatus independently across every corridor they operate. 

    The compliance engine is embedded into the payment flow, not bolted on after the fact.

    For FX, RemitJunction gives disbursing organizations control over their pricing strategy: set your own FX margins, access live market rates, and manage currency conversion in real time. For organizations running large-volume disbursements where basis points matter at scale, this flexibility is operationally significant.

    Organizations that don’t want to build custom front-ends can deploy RemitJunction’s fully branded interfaces. 

    But for enterprises and institutional senders that need deep integration with existing systems, the API-first approach lets your engineering team plug RemitJunction’s bulk remittance payments platform directly into your disbursement workflow — triggering, tracking, and reconciling at whatever volume you operate.

    Who This Is Actually Built For

    Business man working and answering a call

    The use cases for institutional cross-border disbursement on RemitJunction’s bulk payment platform are broader than most people initially assume:

    • NGOs and humanitarian organizations that need to disburse aid or programme funds to last-mile recipients across multiple countries — and need audit-grade documentation to satisfy donor reporting requirements.
    • Telcos running agent commission payouts, airtime reseller payments, or subscriber refunds across footprint markets where the payout mix includes mobile wallets prominently.
    • Banks and financial institutions that want to offer cross-border payroll solutions for Africa-facing corridors without building and licensing an independent remittance operation.
    • Enterprises with distributed workforces, affiliate networks, or supplier bases in emerging markets who need reliable, compliant disbursement infrastructure without the overhead of managing it in-house.

    The Smarter Way Forward for Cross-Border Disbursement

    The era of stitching together five different vendor relationships to run a single disbursement corridor is, mercifully, ending. 

    The maturity of Remittance-as-a-Service infrastructures means that organizations of all sizes can now access enterprise-grade cross-border disbursement capability without enterprise-grade setup costs or timelines.If you’re ready to move past the patchwork and run cross-border disbursements on infrastructure built for the job, explore how RemitJunction powers UK-Africa corridors — or get in touch with the team to discuss your disbursement use case directly.